Blog

  • How to Track Ad Spend Across Meta, Google and TikTok

    How to Track Ad Spend Across Meta, Google and TikTok

    Example scenario: a small skincare brand spends on Meta, Google Shopping and TikTok. Each dashboard claims strong results, and adding up the conversions they report gives more orders than the store received. Meanwhile, the card statement shows charges from all three platforms at different times and amounts, so the founder cannot tell what last month really cost per channel, let alone which channel deserves next month’s budget.

    This is the normal state for brands that track ad spend across multiple platforms without a system. Each platform measures itself, bills on its own schedule, and sets its own budget rules. This guide gives small e-commerce teams a tracking framework: what to measure, a weekly sheet you can copy, a monthly reconciliation routine, and a payment setup that keeps each platform’s charges separate.

    Three reasons multi-platform tracking breaks

    Platforms grade their own homework

    Meta, Google and TikTok each attribute conversions using their own models and windows. A customer who sees a TikTok video, clicks a Meta ad and later searches on Google can be counted by all three. Adding platform-reported conversions together overstates results.

    Billing does not match spending

    Ad platforms usually charge when you reach a billing threshold or a bill date. TikTok, for example, charges at your account’s billing threshold or bill date, whichever comes first, according to TikTok’s help article on automatic payment. So the charges in a given month do not equal that month’s spend.

    Daily spend moves around

    Budgets are not rigid daily amounts. Google Ads can spend up to twice a campaign’s average daily budget on one day for most campaigns, with a monthly cap of 30.4 times the daily budget, as Google’s page on average daily budgets explains. Weekly totals are more useful than daily ones.

    The framework: four numbers per platform, one blended view

    Keep the metric list short so you update it every week.

    1. Spend: from each platform’s dashboard, for the week.
    2. Platform-reported revenue or conversions: useful for comparing campaigns within a platform, not across platforms.
    3. Store revenue and orders: from your store, which is the source of truth.
    4. Blended efficiency: total store revenue divided by total ad spend across all platforms (often called marketing efficiency ratio or blended ROAS).

    Use platform numbers to optimize inside each platform, and the blended number to decide how much to spend overall. When you shift budget between platforms, watch whether blended efficiency improves.

    Template: the weekly ad spend sheet

    WeekPlatformSpendPlatform-reported revenuePlatform ROASCard (last four)Monthly budgetBudget used to dateNotes
    Week 1MetaFill inFill inFormulaMeta cardFill inFormulaNew creative launched
    Week 1GoogleFill inFill inFormulaGoogle cardFill inFormulaShopping feed fixed
    Week 1TikTokFill inFill inFormulaTikTok cardFill inFormulaTesting new audience
    Week 1TotalSumNot summedn/an/aSumSumStore revenue and blended efficiency here

    Leave the “platform-reported revenue” total blank on purpose. It reminds everyone not to add those numbers together.

    Set up tracking hygiene once

    The weekly sheet is only as good as the data behind it. Spend an hour on these basics before you start:

    • UTM parameters on every ad. Use the same pattern on all platforms (for example, source = platform name, medium = paid, campaign = campaign name) so your store analytics can group traffic by channel.
    • One naming convention. Name campaigns the same way everywhere, such as product, audience and date. Matching campaigns across platforms becomes much easier.
    • Store-side order source. Make sure your store records the landing page and UTM source for each order where it can.
    • A post-purchase question. A one-line “How did you hear about us?” survey adds a customer-reported view that no platform controls.

    Decision guide: shifting budget between platforms

    • Blended efficiency rises after you add spend to one platform: keep the change and test a little more.
    • Platform ROAS rises but blended efficiency stays flat: the platform may be claiming sales that would have happened anyway. Hold the budget.
    • A platform spends its budget early every month: check bids and budgets inside the platform before loading more onto its card.
    • A new platform test: give it a fixed test budget and a separate card, and judge it on store revenue after several weeks.

    Monthly reconciliation in six steps

    1. Download each platform’s billing history for the month.
    2. Export the card transactions for each platform’s card.
    3. Match every charge to a platform invoice or receipt.
    4. Note timing differences, such as last month’s spend billed early this month.
    5. Compare total spend from the dashboards with the month’s budget per platform.
    6. Send the totals to your bookkeeper with the invoices attached.

    If all three platforms bill one card, step 3 means sorting a mixed list by merchant name and guessing which charge covers which period. With one card per platform, each card’s statement lines up with one billing history.

    Payment setups compared

    SetupReconciliationIf a payment failsOverspend protection
    One card for all platformsMixed statement, manual sortingAll platforms can pause at onceOnly platform budgets
    One credit card per platformClean per platformOnly that platform pausesPlatform budgets plus each card’s limit
    One prepaid card per platformClean per platformOnly that platform pausesPlatform budgets plus the loaded balance

    Budgets should always be set inside each platform first. A prepaid card is a second ceiling, useful in case a budget is set wrong or a campaign is duplicated by mistake.

    Example setup with Vizovcc

    Vizovcc is one provider you can use for the one-card-per-platform layout. You add crypto such as USDT, USDC, Bitcoin or ETH to an account balance and buy prepaid virtual cards from it, with each card holding its own balance. The site names Meta ads, Google Ads and TikTok Ads among common uses and suggests one card per ad account.

    A small brand might hold three Vizovcc cards, one per platform, and load each with that platform’s monthly budget plus a margin for billing timing. Each card’s last four digits go into the weekly sheet. If you pause a channel, you can freeze its card from the dashboard. All cards support 3D Secure, which some platforms ask for when you add a payment method. For setup steps on each platform, see this guide to virtual cards for ad platforms.

    Keep a few points in mind. Vizovcc does not let you set spend limits or merchant locks on a card, so daily and monthly budgets belong in Ads Manager, Google Ads and TikTok Ads Manager. A card that runs out of balance will cause a failed charge, which can pause campaigns, so top up before billing dates. Each platform decides which cards it accepts, so start with a small charge. Separate cards help with tracking; they do not change anything about each platform’s ad policies, which still apply in full.

    Common questions

    Should I trust platform ROAS at all?

    Use it to compare campaigns and creatives within the same platform. For cross-platform budget decisions, rely on store revenue and blended efficiency.

    How often should I move budget between platforms?

    Make changes weekly or every two weeks, not daily. Platforms need time to stabilize after budget changes, and daily numbers are noisy.

    What if I add a fourth platform later?

    Add a row to the sheet and a card for that platform. The framework scales because each platform stays separate.

    Key takeaways

    • Never add platform-reported conversions together; use store revenue as the source of truth.
    • Track four numbers per platform weekly and one blended efficiency number overall.
    • Billing follows thresholds and bill dates, so reconcile spend and charges separately.
    • One card per platform makes reconciliation a direct match and isolates failed payments.
    • Set budgets inside each platform; a prepaid balance is a backup ceiling, not a replacement.

    Set up the weekly sheet this Monday and fill in last week’s numbers for each platform. When you are ready to separate payments too, consider Vizovcc as one option for a prepaid card per platform.
  • Prepaid Cards for Subscriptions: Pros, Cons and Renewals

    Prepaid Cards for Subscriptions: Pros, Cons and Renewals

    Example scenario: you move your music, cloud storage and a design app onto a prepaid card so they stop cluttering your bank statement. It works well for four months. In month five, the design app’s annual renewal comes due, the card has $14 left, and the payment fails. The app locks your files on a deadline week, and you didn’t see it coming because nothing about a prepaid card warns you ahead of time.

    Using a prepaid card for subscriptions is a popular way to control spending and keep your main card off dozens of sites. It works, with one problem most guides skip: renewals. This article gives a fair look at the pros and cons, explains why recurring payments fail on prepaid cards, and offers a simple routine to stay ahead of the renewal problem.

    How prepaid cards work for subscriptions

    A prepaid card holds money you load in advance. There is no credit line and nothing to repay. When a subscription renews, the merchant charges the card like any other, and the payment goes through only if the balance covers the full amount, including any tax. Many prepaid cards today are virtual, so you add the card number to a service just as you would a bank card.

    The pros

    • Hard spending cap. A subscription can’t charge more than the balance. That is useful for budgeting and for limiting surprise price increases.
    • Your main account stays private. If a service is breached, the leaked number has no link to your bank account.
    • Forgotten renewals hit a ceiling. A trial you forgot to cancel can only take what is on the card.
    • One place to see every subscription. If all your subscriptions sit on one card, its transaction list is your subscription list.
    • No credit check. Prepaid cards are usually available without one.

    The cons

    • Some merchants refuse prepaid cards. Services that bill on a schedule may decline prepaid cards, either at sign-up or only on renewal.
    • Renewals can fail silently. A low balance on renewal day means a declined payment, and the merchant may pause your account.
    • Fees. Many prepaid cards charge for issuing, loading or transactions. Read the fee list before you compare.
    • Different protections. In the US, the CFPB’s prepaid card rights page explains that you generally get fraud and error protections if your prepaid card is registered. Cards from providers outside the US follow their own terms, so check what applies before you load large amounts.
    • Card expiry. When a prepaid card expires, every subscription on it needs a new card, just like a bank card.

    The renewal problem nobody mentions

    Prepaid cards are best at the thing that makes subscriptions annoying: they stop charges when the money runs out. That same feature is what breaks the subscriptions you want to keep. Four renewal traps cause most of the trouble:

    Annual renewals

    Monthly charges drain a card slowly and predictably. An annual plan drops twelve months of cost onto the card on one day, often long after you loaded it.

    Tax and currency

    A plan listed at one price may be charged with sales tax or VAT added, or converted from another currency. A card loaded with exactly the list price will fail.

    Price increases

    Services raise prices with an email notice. If you budgeted your card to the old price, the first renewal at the new price fails.

    Retry and suspension rules

    After a failed renewal, some merchants retry for a few days, others suspend the account straight away. Some cards are also set up by their issuer to refuse transactions marked as recurring, so the sign-up works and the first renewal doesn’t.

    Prepaid vs. debit vs. credit for subscriptions

    FactorPrepaid cardDebit cardCredit card
    Spending capBalance on the cardYour checking balanceYour credit limit
    Forgotten renewalStops when the balance runs outKeeps chargingKeeps charging
    Exposure if breachedOnly the card balanceYour checking accountIssuer’s money until disputed
    Merchant acceptanceVaries; some decline prepaidBroadBroadest
    Renewal reliabilityDepends on you keeping it fundedHigh while the account has moneyHigh
    Dispute protectionsDepends on issuer and registrationRegulated in many countriesUsually strongest

    A 5-step routine to fix the renewal problem

    1. List every subscription on the card with its renewal date and full price. Include tax and note whether it bills monthly or annually.
    2. Add a buffer. Keep the balance above the next 30 days of renewals plus roughly 10% for tax, currency conversion and price changes.
    3. Check the balance weekly. Thirty seconds on a Sunday is enough. Put it in your calendar.
    4. Set reminders before annual renewals. Two weeks ahead, decide whether to keep the plan and make sure the card can cover it.
    5. Test new services with the first renewal. The sign-up charge proves little. Watch the first renewal to confirm the merchant accepts the card for recurring billing.

    When a prepaid card is the right choice

    • You want a firm subscription budget and are happy to check a balance weekly: good fit.
    • You keep forgetting to cancel trials: good fit, as long as you still cancel properly.
    • Your bank card is declined by foreign services: a prepaid card in the right currency can help, if the service accepts prepaid cards.
    • A critical service must never lapse, such as hosting for a live business site: use a card with automatic funding, or keep a large buffer.
    • You need strong dispute rights: a credit card is usually better.

    Example: keeping ahead of renewals with Vizovcc

    Vizovcc sells prepaid virtual cards that you buy with crypto from an account balance. Each card has a fixed loaded balance, and the Vizovcc dashboard shows the balance of every card on your account, which makes step three of the routine above quick. You can hold several cards on one account, for example one for monthly services and one for annual plans, so a large yearly renewal doesn’t drain the card your monthly subscriptions rely on. Cards support 3D Secure, card pages show Apple Pay and Google Pay compatibility, and you can freeze a card from the dashboard between uses or after cancelling a plan. Card pages show the price and how it is split between the issue charge and the spendable balance. If AI tools make up part of your list, see Vizovcc’s guide to cards for ChatGPT, Claude and other AI plans.

    Limits to know: the dashboard shows balances, but it doesn’t know your renewal dates, and Vizovcc doesn’t offer merchant locks or per-card spending limits you set, so the weekly check is still your job. Each service decides whether it accepts prepaid cards, and card purchases are final, so match the card’s currency and balance to the subscriptions you plan to move.

    Frequently asked questions

    Why did my prepaid card work at sign-up but fail on renewal?

    Usually a low balance, tax added to the price, or a card or merchant that rejects recurring transactions. Check the balance first, then ask the merchant whether it accepts prepaid cards for recurring billing.

    Can I use one prepaid card for all my subscriptions?

    Yes, and it keeps tracking simple. Separate cards for annual and monthly plans make the balance easier to manage.

    Will a failed renewal cancel my subscription?

    Not necessarily. The merchant may retry, pause your account or keep the subscription open with an unpaid balance. Cancel properly if you no longer want it.

    Key takeaways

    • Prepaid cards cap spending and protect your main account, but some merchants decline them.
    • The renewal problem comes from annual plans, tax, price increases and retry rules.
    • Keep a 30-day buffer, check the balance weekly and test the first renewal of every new service.
    • Splitting monthly and annual plans across two cards keeps big renewals from draining everything.
    • Check the protections that apply to your card before loading large amounts.

    List your subscriptions and their renewal dates this week, then decide whether a prepaid card fits. If it does, compare cards on Vizovcc and pick one whose currency and balance cover the next month of renewals with room to spare.

  • Startup Burn Rate Control: A Card Budget for Each Department

    Picture this example. A seed-stage startup plans for 18 months of runway. Six months in, the founder prepares the board update and finds that monthly burn is well above plan. Nothing dramatic happened: a few more AI tool seats, an ad test that kept running, a second analytics tool, two conferences. Every purchase made sense on its own. They all went on the founder’s card or the one company card that the whole team uses, and nobody was watching a department total until the bank balance made the point for them.

    Burn creeps up at the point of purchase, not in the spreadsheet. Startup spend management works when budgets live where money is spent. This guide explains how to set department budgets that hold, what card-level controls can do, and how a small team can get most of the benefit without heavy software.

    Burn rate basics in one minute

    • Gross burn is everything you spend in a month.
    • Net burn is gross burn minus revenue for the same month.
    • Runway is cash in the bank divided by net burn, in months.

    Payroll is usually the largest and most predictable line. The lines that drift are the variable ones: software, advertising, cloud, travel and contractors. Those are mostly paid by card, which is why cards are the right place to control them.

    Why spreadsheet budgets don’t hold

    They describe the past

    A budget spreadsheet updated at month end tells you what was spent. By then, the money is gone and the next month’s renewals are already scheduled.

    No one owns the line

    If “Software” is one line for the whole company, every team adds to it and no team answers for it.

    One card hides everything

    When the whole team pays with one card, department totals have to be rebuilt by hand from merchant names. That work tends to be skipped exactly when it matters most.

    Five ways to enforce department budgets

    MethodHow it stops overspendEffortBest for
    Spreadsheet trackingIt doesn’t; it reports overspend after the factLow to set up, high to maintainVery small teams with few vendors
    Approval before purchaseA person says noSlows every purchaseLarge, irregular purchases
    Budgets inside each platformAd accounts, cloud consoles and SaaS seats stop or alert at a capMedium: one setting per platformVariable spend such as ads and usage billing
    Separate prepaid card per departmentThe card can’t pay more than its balanceLow to mediumSmall teams that want hard ceilings without new software
    Spend-management platform with card limitsPer-card limits, merchant rules, approvals and rolesHigher cost and setupGrowing teams with department heads managing their own budgets

    These methods stack. A common setup for an early-stage company is a separate card per department, budgets set inside each ad and software platform, and approval only for purchases above a fixed amount.

    What card-level controls usually include

    Dedicated spend-management platforms typically offer per-card spending limits, monthly or per-transaction caps, merchant category restrictions, approval workflows and role-based access so a department head can see and manage only their own budget. They are useful once a company has several budget owners. They also cost money and setup time, which is why many seed-stage companies start with simpler structure: separate cards and platform-level caps.

    Setting up department budgets, step by step

    1. Set the target burn. Start from the runway you need to reach the next milestone, then work back to a monthly net burn.
    2. Split the variable spend by department. Engineering (cloud, dev tools), marketing (ads, design tools), sales (CRM, data tools), operations (finance and admin software, travel).
    3. Name one owner per budget. The owner answers for the total, approves new tools and reviews charges.
    4. Give each budget its own card. One card per department, or per budget bucket such as “paid ads” or “AI tools” if one bucket moves faster than the rest.
    5. Set caps inside the platforms. Use ad account spending limits and campaign budgets, cloud budget alerts and seat limits on SaaS tools. These control the pace of spend, while the card shows the total.
    6. Review weekly, briefly. Fifteen minutes per week: each card’s spend against its budget, new merchants and upcoming renewals.
    7. Re-forecast monthly. Update runway with actual burn and move budget between departments on purpose, not by accident.
    8. Agree the stop rules in advance. For example: if a department hits 90% of its monthly budget, new tools wait until next month.

    Decision guide: how much structure do you need?

    • Fewer than ten people and one budget owner: separate cards per department plus platform caps are usually enough.
    • Several budget owners who need to manage their own spend: look at a spend-management platform with roles and per-card limits.
    • Ad or cloud spend is the main source of drift: start with caps inside those platforms, then give each its own card.
    • Investors ask for spend by department: separate cards make that report a lookup instead of a reconstruction.

    Example: department cards with ZenVCC

    ZenVCC is a prepaid virtual card platform that fits the “separate card per department” row in the table. You fund one company balance with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), each deposit is checked on its blockchain before it is credited, and you buy a separate prepaid Visa, Mastercard or American Express card for each department or budget bucket. Supported uses include ad platforms such as Meta, Google, TikTok and LinkedIn, and software such as Microsoft 365, Slack, Notion, Canva and AI tools.

    • Hard ceilings. A prepaid card can’t pay more than its balance, so a department card can’t overspend.
    • Simple costs. A one-time $10 issue fee per card on top of its price, $0.10 per payment and no monthly fee, so adding a card for a new budget bucket adds no recurring cost.
    • Three-year validity from the day each card is ready, so platform payment details rarely need updating.
    • Refund if a card can’t be prepared, including the issue fee.

    It is important to be clear about what it isn’t. ZenVCC has no per-card limits, merchant rules or approval engine, so monthly budgets are set inside each platform and in your weekly review. It also has no team roles or sub-accounts: whoever signs in sees every card, so department heads can’t manage their own cards. Keep the login with the founder or finance lead. Cards also can’t be topped up from the dashboard, so check what each card covers before you buy and plan budget periods around that. For founders comparing cards, the list of prepaid card options shows each card’s total before purchase. Each platform decides which cards it accepts, and platform policies still apply; Google Ads, for example, doesn’t take prepaid cards for postpay billing, and several cloud providers, including AWS, Google Cloud and Microsoft Azure, refuse prepaid or virtual cards, so an engineering cloud bill may need another payment method. ZenVCC cards also can’t complete a payment that asks for a 3-D Secure code, because the dashboard doesn’t show those codes.

    Mistakes to avoid

    • Budgeting by vendor but paying from one card. The budget can’t hold if the card doesn’t match it.
    • Skipping platform caps because the card is prepaid. The card limits the total; platform caps control how fast it is spent.
    • Annual plans without review. An annual renewal can consume a department’s monthly budget in one charge. Track renewal dates.
    • Treating every overspend as a failure. Sometimes a channel is working and deserves more budget. Move it deliberately at the monthly re-forecast.

    Key takeaways

    • Burn drifts at the point of purchase, so budgets have to live on cards and inside platforms, not only in a spreadsheet.
    • Give each department or budget bucket an owner and its own card.
    • Platform caps control pace; prepaid cards set a hard total.
    • Review weekly for fifteen minutes and re-forecast runway monthly.
    • Add a full spend-management platform when you have several budget owners who need roles and per-card limits.

    This week, split last month’s card charges by department and see which line moved most. Give that department its own card first. If you want a prepaid option with no monthly fee for department cards, take a look at ZenVCC.

  • Card Testing Fraud: How Attacks Work and How to Limit Damage

    Card Testing Fraud: How Attacks Work and How to Limit Damage

    Here is an example of how it often starts. A finance lead reviewing the company card sees a $1.00 donation to a charity site nobody has heard of. Two days later there is a $2.49 charge at an online game store. Nobody flags either one, because they are too small to matter. The following week, the same card pays for $640 of electronics.

    The small charges were not mistakes. They were tests. Card testing fraud is how criminals find out which stolen card numbers still work before they spend them. This guide explains how the attack works, what the warning signs look like for cardholders and merchants, which controls stop which stage, and how separate virtual cards limit the damage when a test succeeds.

    What card testing fraud is

    Card testing is the step between stealing card data and using it. Fraudsters often hold large batches of card details and do not know which are still active. They run small payments or card verifications to sort live cards from dead ones, then either spend the live cards or sell them as verified. Stripe’s documentation on card testing lists other names for the same activity, including carding, account testing, enumeration and card checking.

    How a card testing attack works

    Stage 1: getting card data

    Card details come from merchant breaches, phishing pages, malware on checkout pages and skimming. In an enumeration attack, also called a BIN attack, fraudsters skip theft entirely and generate plausible card numbers within a known card number range, then guess the expiry date and security code.

    Stage 2: running the tests

    Automated scripts send many attempts through a merchant’s checkout, often one with weak protections. Two methods are common. Small payments are used because cardholders tend to ignore them. Card setup flows, where a merchant saves or verifies a card without charging it, are popular because, as Stripe notes, these verifications do not usually show up on cardholder statements.

    Stage 3: sorting the results

    Each approval or decline tells the fraudster something. Approved cards go on a “valid” list. Declines are discarded.

    Stage 4: cashing out

    Valid cards are used for larger purchases, often of goods that are easy to resell, or sold on to other criminals at a higher price because they are confirmed to work.

    Warning signs

    For cardholders

    • Small charges, often under a few dollars, from merchants you do not recognize.
    • Donations to charities you did not choose. Donation pages are a common testing ground.
    • Authorization alerts or declines you did not trigger.
    • Several small charges on the same day from unrelated merchants.

    For merchants

    • A sudden spike in failed or declined payments.
    • Many low-value payments with nonsensical names or email addresses.
    • Large numbers of cards added to new accounts, often from the same network address.
    • Rising disputes weeks later, when cardholders notice the charges that went through.

    Merchants pay for card testing too: disputes, extra fees and a higher decline rate that can make legitimate customers’ payments look riskier to issuers.

    Which controls stop which stage

    No single control stops card testing. Each one works at a different point in the attack, and some are run by merchants, some by issuers and some by you.

    ControlRun byBlocks the testLimits the cash-out
    CAPTCHA, rate limits and login before checkoutMerchantOftenIndirectly
    Issuer fraud monitoringCard issuerSometimesSometimes
    3-D Secure checksMerchant and issuerWhere the merchant requests itWhere the merchant requests it
    Spending limits on a cardCard providerNo, small tests passYes, up to the limit
    Merchant locksCard providerYes, at every other merchantYes
    Single-use numbersCard providerYes, once usedYes
    Separate prepaid card per vendorYouNoYes, to the funds on that card

    The pattern is clear. Merchant controls fight the test itself. Card-level controls accept that some tests will pass and focus on making the cash-out small or impossible.

    What to do if you spot a test charge

    1. Act on the small charge. Do not wait to see whether a larger one follows. The small one is the warning.
    2. Contact your card issuer. Report the charge as unauthorized and ask for a replacement card.
    3. Dispute any charges that went through. Follow your issuer’s process and keep dates and reference numbers.
    4. Work out where the card was stored. List the merchants that had it on file. One of them may have been the source.
    5. Update the services that used the card. The fewer services share a card, the shorter this list is.
    6. Split your cards going forward. Give important vendors their own cards so the next test only reaches one of them.

    How virtual cards limit the damage

    Virtual cards cannot stop a fraudster from testing a number they already hold. What they change is how much a successful test is worth.

    • Spending limits cap the cash-out at a set amount.
    • Merchant locks make a stolen number useless anywhere except its original merchant.
    • Single-use numbers are dead after one purchase, so there is nothing to test.
    • Separate prepaid cards per vendor cap the cash-out at whatever is on that card, and keep the stolen number away from your main account.

    Example: containing exposure with ZenVCC

    ZenVCC is a prepaid virtual card platform, and it covers only the last item on that list. To be direct: it does not offer spending limits you set per card, merchant locks or single-use numbers. If those controls are a must, look for a provider that offers them.

    What it does offer is a separate prepaid card for each vendor, bought from one balance funded with crypto (Bitcoin, USDT on TRC-20 or Solana, TRX or SOL), with each deposit checked on its blockchain before it is credited. Because a card can only spend what is on it, a fraudster who passes a test can take at most that card’s funds. Your bank card is never on file with the vendor, and other vendors keep working because they use different cards. For background, ZenVCC publishes a plain-English explainer on how virtual cards work.

    Practical details and limits:

    • Costs. A one-time $10 issue fee per card, $0.10 per payment and no monthly fee, so splitting vendors across many cards does not add recurring costs.
    • Validity. Three years from the day the card is ready.
    • Visibility. The ZenVCC dashboard does not list card payments, so you will not see small test charges there. Check vendor billing pages and receipts instead.
    • If details leak. Its guidance is to remove the card from every site that saved it, buy a new card for those payments and contact support with the card’s reference number.
    • 3-D Secure. The dashboard does not show 3-D Secure codes, so a payment that asks for one cannot be completed with these cards. Merchants that require 3-D Secure will decline them.
    • Funds stay on the card. There are no transfers from a card back to the balance, so load each card with what that vendor needs, not more.

    Key takeaways

    • Card testing fraud uses small payments or card verifications to find working stolen cards before a larger cash-out.
    • A small charge from an unknown merchant is the warning sign. Report it immediately.
    • Merchant controls such as CAPTCHA and rate limits fight the test. Card-level controls limit the cash-out.
    • Spending limits, merchant locks and single-use numbers are strong card controls where your provider offers them.
    • Separate prepaid cards per vendor cap what any one stolen number can lose, even without those features.

    Look at your last three months of statements for small charges you cannot explain, and give your most important vendors their own cards. If a prepaid card per vendor with no monthly fee fits your setup, compare ZenVCC with the cards you use now.

  • Swan Valley Tours: Your Guide to Local Wine Experiences

    Swan Valley Tours: Your Guide to Local Wine Experiences

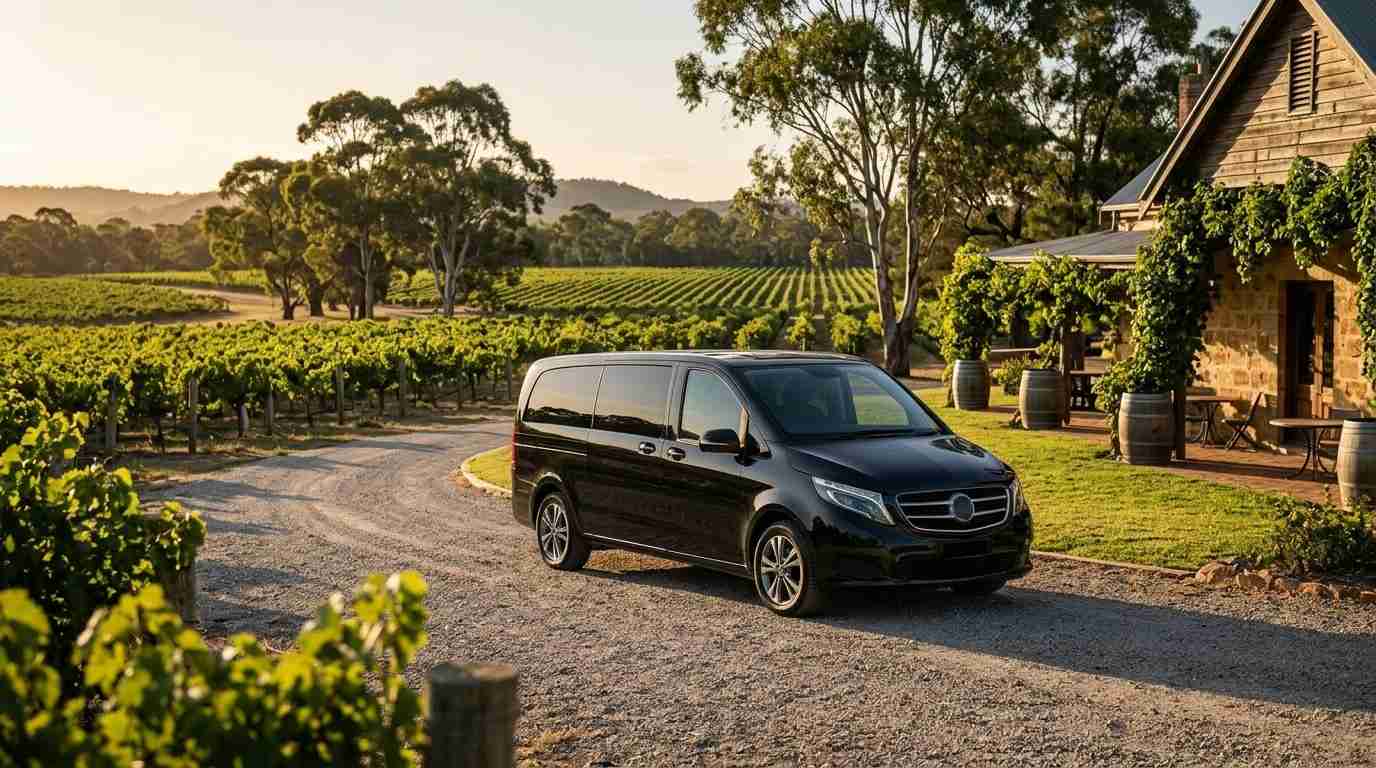
    Elegant Charters, a Perth-based chauffeur and passenger transportation provider, is introducing Swan Valley Tours as part of its private transportation and personalised travel services. The new offering aims to provide visitors, residents and groups with convenient transport options for exploring the Swan Valley wine region and its surrounding attractions.

    Opening Summary: Expanding Private Tour Transportation in Perth

    The introduction of Swan Valley Tours reflects growing interest in convenient, comfortable transportation for regional sightseeing and wine experiences around Perth. Through its chauffeur-driven vehicles and group transport options, Elegant Charters aims to make travel between Perth and the Swan Valley more accessible for individuals, families and organised groups.

    Based in Southern River, Western Australia, the company provides transportation services across Perth, including airport transfers, corporate travel, private bookings, weddings, events and customised journeys.

    Market Challenge: Convenient Transportation for Regional Wine Experiences

    The Swan Valley is a popular destination for visitors interested in wine experiences, local food, regional attractions and scenic surroundings. However, arranging transportation for a full-day regional visit can present practical challenges, particularly for groups and travellers who prefer not to drive.

    Visitors may need to coordinate multiple stops, accommodate different group sizes and arrange reliable return transportation. For those planning wine-focused outings, having a dedicated driver can also provide a more convenient way to enjoy the experience without managing the journey themselves.

    Private chauffeur services and pre-arranged group transportation offer an alternative to self-driving and conventional point-to-point travel.

    Company Response: Personalised Swan Valley Tours

    Through its Swan Valley Tours service, Elegant Charters is extending its transportation offering to accommodate visitors planning regional sightseeing and wine-related outings.

    The service is designed around private transportation, allowing customers to arrange journeys according to their travel requirements, group size and preferred schedule.

    Customers can explore potential itineraries involving wineries, cellar doors, local food destinations and other regional attractions while having transportation arranged for the journey.

    The company’s approach focuses on providing a practical transport solution for travellers seeking flexibility, comfort and convenient access to the Swan Valley from Perth.

    Service Details: Transportation Options for Different Groups

    Elegant Charters operates a fleet designed to accommodate a range of passenger requirements, from individual travellers to larger groups.

    Available vehicle categories include:

    • Sedans: Suitable for individuals, couples and smaller private bookings.
    • SUVs: An option for passengers seeking additional space and comfort.
    • 4–7 seater vehicles: Designed for families and small groups.
    • 13–24 seater minibuses and maxi cabs: Suitable for larger groups, private outings and organised travel.

    In addition to Swan Valley Tours, the company provides airport transfers, corporate transportation, wedding transport, hotel transfers, event transportation, FIFO transfers, cruise transfers and long-distance journeys.

    Additional details are available at: https://share.google/gH9qsqNjtvVagBcyp

    Additional service features include 24-hour availability, online booking, personalised travel arrangements, flexible payment options and baby-seat options for eligible bookings.

    By offering several vehicle categories, Elegant Charters aims to accommodate different passenger requirements for private regional travel.

    Company Background: Chauffeur and Transport Services Across Perth

    Elegant Charters provides professional chauffeur services and private passenger transportation throughout Perth and surrounding areas.

    The company serves a variety of travel requirements, including airport pickups and drop-offs, business journeys, family transportation, private tours and group travel.

    Its fleet-based approach allows customers to select transportation according to passenger numbers and journey requirements. The company also offers door-to-door transportation, personalised travel planning and online booking facilities.

    Through its expanded tour transportation services, Elegant Charters continues to develop options for customers seeking private and group travel beyond conventional airport and city transfers.

    Executive Quote

    Suggested executive statement – pending company approval:

    “Introducing Swan Valley Tours gives customers another way to experience the region while having their transportation arranged in advance. We want to make private and group travel more convenient by providing suitable vehicles and flexible arrangements for different travel needs,” said a spokesperson for Elegant Charters.

    Future Outlook: Supporting Regional Travel and Tourism

    Elegant Charters plans to continue developing its private transportation services to address the changing requirements of Perth residents, business travellers and visitors.

    The expansion into Swan Valley Tours represents an opportunity to support regional sightseeing through pre-arranged chauffeur and group transportation.

    As interest in personalised travel experiences continues, the company intends to maintain a service offering that accommodates airport transfers, private tours, corporate journeys and other transportation requirements across the Perth region.

    Travellers interested in arranging transportation for a Swan Valley visit can find further information and booking details through the company’s website.

    About Elegant Charters

    Elegant Charters is a Perth-based chauffeur and passenger transportation provider located in Southern River, Western Australia. The company offers airport transfers, private chauffeur services, corporate transportation, group travel, regional tours, wedding transport, event transfers and long-distance journeys.

    Its fleet includes sedans, SUVs, 4–7 seater vehicles and 13–24 seater minibuses and maxi cabs. With 24-hour availability, online booking facilities and personalised travel arrangements, Elegant Charters serves individuals, families, businesses and groups requiring transportation throughout Perth and surrounding regions.

    Media Contact

    Company: Elegant Charters – Airport Transfers Perth – Chauffeur Service Perth
    Location: Southern River, Western Australia, Australia
    Phone: +61 458 655 640
    Website: https://elegantcharters.com.au/

  • Municipal Stump Grinding Keeps Cincinnati Public Spaces Safe

    Municipal Stump Grinding Keeps Cincinnati Public Spaces Safe

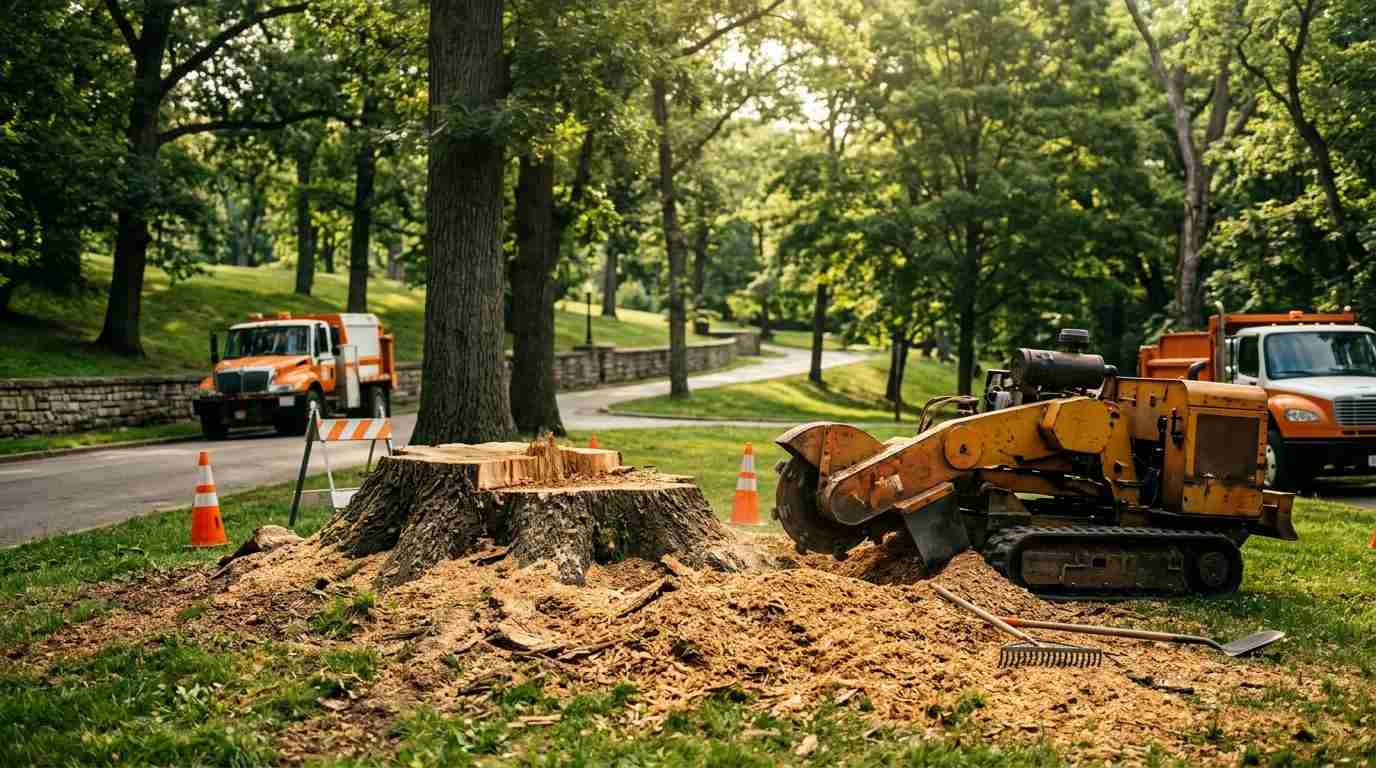
    Valentine Services – Stump Grinding is expanding its stump grinding services to address the needs of municipal properties throughout Cincinnati, Ohio, and surrounding communities. The service provides municipalities and public property managers with access to professional stump removal, surface root grinding and site cleanup to help maintain safer, more accessible outdoor spaces.

    Tree removal is often necessary for public property maintenance, storm cleanup, infrastructure improvements and landscape management. However, the remaining stumps and exposed roots can create obstacles for pedestrians, maintenance crews and groundskeeping equipment. Addressing these conditions is an important part of maintaining public parks, walkways, landscaped areas and other municipal properties.

    Addressing Stump Hazards on Municipal Properties

    Municipal properties experience regular landscaping and maintenance demands. When trees are removed, remaining stumps can interfere with mowing, landscaping projects and the intended use of public spaces.

    Unremoved stumps may also contribute to tripping hazards and create obstacles for routine property maintenance. Professional stump grinding provides a way to address these issues without requiring complete excavation of every root system.

    Valentine Services – Stump Grinding is making its stump grinding capabilities available to municipal property managers and other organizations responsible for maintaining outdoor public spaces in the Cincinnati area.

    Company Expands Its Stump Grinding Services

    The company’s municipal-focused services build on its existing experience serving residential, commercial and contractor clients throughout Cincinnati and Northern Kentucky.

    Valentine Services uses specialized stump grinding equipment to reduce unwanted tree stumps below ground level. Its services also include surface root grinding, large stump removal, wood chip cleanup and site restoration.

    Additional details are available at: https://share.google/FhICefWA6JHjY7oiz

    Depending on project requirements, property managers can request stump grinding to address individual stumps or multiple locations. The work is intended to help prepare affected areas for ongoing landscaping, maintenance or future property improvements.

    Services Available for Municipal Properties

    Municipal property managers and organizations overseeing public outdoor spaces can inquire about several stump-related services, including:

    • Municipal stump grinding: Removal of remaining tree stumps from public and managed properties.
    • Surface root grinding: Reduction of exposed roots that may interfere with pedestrian access and landscaping.
    • Large stump removal: Grinding services for larger tree stumps that require specialized equipment.
    • Wood chip cleanup: Removal or management of grinding debris, depending on project requirements.
    • Site restoration: Preparation of affected areas for subsequent landscaping and property maintenance.

    The company also provides residential and commercial stump grinding throughout its service region.

    Serving Cincinnati and Northern Kentucky

    Valentine Services – Stump Grinding serves Cincinnati and surrounding communities, including Blue Ash, Mason, West Chester, Fairfield, Loveland, Hamilton, Florence, Covington, Erlanger, Burlington and Hebron.

    The company is licensed and insured and provides estimates for property owners, businesses, contractors and organizations evaluating stump grinding projects.

    Municipal departments and public property managers can contact the company to discuss project requirements, site conditions and service availability.

    About Valentine Services – Stump Grinding

    Valentine Services – Stump Grinding provides professional stump grinding and stump removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company works with homeowners, businesses, property managers, contractors and other clients seeking solutions for unwanted tree stumps, surface roots and related property maintenance concerns.

    Its services include residential stump grinding, commercial stump grinding, root grinding, large stump removal, wood chip cleanup and site restoration. Valentine Services is licensed and insured and provides estimates for projects throughout its regional service area.

    Executive Comment

    “Municipal properties require consistent attention to landscaping, accessibility and general maintenance. Our stump grinding services give municipal property managers another option for addressing remaining tree stumps and surface roots as part of their property maintenance work.”

    — Valentine Services Representative

    Supporting Cincinnati’s Ongoing Property Maintenance Needs

    As Cincinnati communities continue maintaining parks, landscaped areas, public grounds and other outdoor spaces, stump removal remains one consideration in long-term property upkeep.

    Valentine Services – Stump Grinding plans to continue providing stump grinding services to residential, commercial and municipal clients throughout Greater Cincinnati and Northern Kentucky. The company encourages municipal representatives and property managers to contact its team to discuss upcoming projects and service requirements.

    For service information or estimates:

    Valentine Services – Stump Grinding
    Phone: 513-570-4626
    Email: bikemanjrv95@gmail.com
    Website: https://www.513stumps.com/

  • Apple ID and Google Play Payment Methods: Why Prepaid Cards Get Declined and What Works

    Apple ID and Google Play Payment Methods: Why Prepaid Cards Get Declined and What Works

    You try to add a prepaid or virtual card to your Apple Account or Google Play, and it comes back with “payment method declined” or “this card can’t be used.” The same card works on websites. App stores are stricter than most merchants: they tie your account to one country, verify the card before they store it, and in Google’s case publish a list of card types they don’t accept at all.

    Quick answer

    1. Your store country and your payment method’s country must match. Neither store lets you switch country freely.

    2. Both stores verify a card when you add it, so the card needs a live balance and correct billing details.

    3. Google Play’s US help page lists virtual credit cards as not accepted. Apple doesn’t publish a prepaid rule, so results vary.

    4. If a card won’t attach, gift cards for your country are the reliable fallback.

    Store country: the rule that decides everything else

    Both app stores bind your account to one country or region. That country decides prices, currency, available apps and which payment methods you can add.

    Apple. Apple’s help page on changing your Apple Account country or region says you may need a valid payment method for the new country, and that before changing you have to spend your store balance, cancel subscriptions and leave Family Sharing if that blocks the change. Apple’s list of accepted payment methods is published country by country.

    Google Play. Google’s help page is more explicit. To change your Play country you must be in that country and have a payment method from it. After a change you have to wait at least 90 days before changing again, and your Google Play balance stays linked to the country where you earned it.

    The practical result is simple: a card from one country won’t attach to a store account set to another country, and the stores don’t want you to switch country to make it fit. If you have actually moved, follow the official change process. If you haven’t, the right fix is a payment method from your own country, not a different store country.

    Why prepaid and virtual cards fail more often here

    Assuming the country matches, the failures come from four mechanisms.

    1. Explicit exclusions. Google Play’s US help page lists the payment types it doesn’t accept. “Virtual Credit Cards (VCC)” are on that list, together with wire transfers, Western Union, MoneyGram, HSA cards, transit cards and escrow-type payments. If your card is a virtual credit card, a decline on Google Play in the US is a policy, not a fault. Other countries’ pages have their own lists. [VERIFY: Google Play accepted-methods page for each target country]

    2. Verification on add. When you add a card, the store checks that it is real and active, typically with a small or zero-amount authorization that is later reversed. [VERIFY: Apple’s and Google’s current verification amounts] A prepaid card with no balance, or one whose issuer declines that kind of check, fails before anything is bought. Apple also says some payment methods must be verified through the bank’s app, a text message or another method.

    3. BIN and card type. The store’s processor reads the card’s BIN, the first 6 to 8 digits, and sees the issuing country, the network and whether the card is credit, debit or prepaid. Country mismatches and some prepaid programs are rejected at this step.

    4. Billing address (AVS). The billing address on the account is checked against the issuer’s records. An address that doesn’t match, or is in a different country from the card, causes a decline.

    Apple vs Google Play at a glance

    QuestionApple AccountGoogle Play
    Is the account tied to one country?YesYes
    Can you change country freely?No: balance, subscriptions and Family Sharing can block it; a payment method for the new country may be neededNo: you must be in the new country with a local payment method; 90-day wait between changes
    Published prepaid policy?Not stated on the payment methods page; it lists “most credit and debit cards” by countryUS page excludes virtual credit cards; prepaid not addressed
    Card verification on addYes; some methods need bank-app or text verificationYes [VERIFY: amount]
    Balance optionsApple Account balance via Apple Gift Cards, in many countriesGoogle Play balance and gift cards, tied to the country
    What happens to the balance on a country changeMust be spent before the changeStays with the original country

    What works: a decision procedure

    Work through these in order. The first one that fits is your answer.

    1.  Check your store country. On iPhone, it’s under Settings > your name > Media & Purchases. On Google Play, it’s under Settings > General > Account and device preferences. It should be the country where you live.

    2.  Check the card’s BIN country and type. If the card was issued for a different country, it won’t attach. Don’t change the store country to fit it.

    3.  If you have a local bank card, use it. A credit or debit card from your country, with the billing address the bank has on file, is the method both stores are built around.

    4.  If you’re on Google Play and the card is a virtual credit card, stop. Google’s list excludes it in the US. Use another method from the list.

    5.  Try carrier billing or PayPal where your country offers them. Both stores list these for many countries.

    6.  Use gift cards for your country. Apple Gift Cards and Google Play gift cards bought from local retailers add balance without a card on the account. This is the reliable route when no local card works.

    7.  If a prepaid card is your only card, make sure it is issued for your country, has a balance above the verification amount, uses the exact billing address and can pass a 3D Secure or bank-app check. Then try once and accept the result.

    Step 6 deserves more attention than it gets. Gift cards are tied to the store country, they need no card verification, and they keep subscriptions inside a fixed budget. For many people in countries with limited card access, they are the intended solution.

    Subscriptions and renewals on a prepaid card

    If a prepaid card does attach to your account, the renewals are the next risk. Both stores charge subscriptions automatically on the renewal date, then retry for a grace period if the charge fails. On a prepaid card, the balance has to be in place on renewal day, not later. Keep a calendar of renewal dates, and top up before them.

    Family Sharing on Apple and the family payment method on Google Play both charge the organizer’s payment method. If the organizer’s card is prepaid, every family member’s purchases draw on that one balance.

    One example of a crypto-funded card in this setting

    A crypto-funded prepaid card is one option for people whose local cards don’t work online, but only within these rules. VCCBuy’s Apple payments page describes one setup: a prepaid Visa or Mastercard funded with USDT, USDC or other supported coins, with a billing name and address saved per card and 3D Secure codes requested in the dashboard, each shown for 10 minutes. Before you try any card on an app store, a BIN lookup (VCCBuy offers a free one) shows the issuing country and card type the store will see. If the country doesn’t match your store country, the card isn’t the right tool. Use gift cards or a local card instead. Prepaid cards are declined by some merchants and settings, and both app stores make their own checks.

    FAQ

    Can I change my Apple Account or Google Play country to match my card? Only if you have actually moved. Apple may require a payment method for the new country and Google requires you to be in it, with a 90-day wait between changes. Changing country just to fit a card isn’t what these processes are for, and it can strand your balance.

    Why does Google Play reject my virtual card when websites accept it? Google Play’s US help page lists virtual credit cards as not accepted. Websites use their own rules. Use a card from your country, a listed method or a Google Play gift card.

    Does Apple accept prepaid cards? Apple’s payment methods page lists “most credit and debit cards” by country and doesn’t state a prepaid rule. Some prepaid cards attach and some don’t, depending on the issuer, the country and the verification step. Apple Gift Cards are the dependable alternative.

    Conclusion

    App store payments fail mostly because of store-country binding and card verification, not because of the card’s balance. Keep your store country accurate, use a payment method from that country, and fall back on local gift cards when a card won’t attach. If you want a crypto-funded card for the services that do accept prepaid cards, VCCBuy is one option to compare with local bank cards.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about how app stores verify cards and why store country decides which payment methods work.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • Steam Purchases With a Virtual Card: Currency, Region and Billing Address Rules

    Steam Purchases With a Virtual Card: Currency, Region and Billing Address Rules

    You add a virtual card to Steam, enter your address, and the purchase fails with “your billing address doesn’t match your current country” or a vague “unexpected error.” The card has money on it and works elsewhere. On Steam, the card is only one part of the check. Steam also compares your store country, your location and the country the card was issued in, and all three have to agree.

    Quick answer

    1. Your Steam store country must match where you live and are buying from.

    2. The card should be issued for that same country and carry a billing address there. Check the card’s BIN country before you try.

    3. If the card’s country doesn’t match, don’t change addresses or use a VPN. Use a local payment method or Steam Wallet codes sold for your country.

    4. The remaining declines are usual card issues: balance, AVS, 3D Secure.

    What Steam checks before your card is even charged

    A Steam purchase passes through two sets of checks: Steam’s own rules, then the card authorization.

    Steam’s rules come first. Every account has a store country. It sets the currency of prices and of your Steam Wallet, and decides which payment methods appear at checkout. Steam’s support guidance is that you buy in the region where you are located, using a payment method associated with a local address. The research behind this post found the same pattern in Steam’s community forums: purchases fail when the card was issued in a different country from the account’s store country, and Steam Support’s answer is to use a payment method from that country.

    The card authorization comes second. Steam’s payment processor sends the request to the issuer with the amount, currency and billing details. The issuer checks the balance, the address verification (AVS) result and, in some regions, 3D Secure.

    So a card can be in perfect order and still fail, because Steam rejected the combination before the issuer was ever asked.

    The four signals that have to agree

    SignalWhere Steam gets itWhat you control
    Store countrySet on your account; changes only by buying from a new country of residenceKeep it accurate. Change it only when you actually move.
    Current locationYour network location at checkoutNothing to “fix”. Buy from where you are.
    Card countryThe card’s BIN, the first 6 to 8 digitsChoose a card issued for your country
    Billing addressWhat you type at checkoutEnter the address the card issuer has on file

    The error “billing address doesn’t match current country” usually means the address or the card points to one country while your store country or location points to another. Typing a different address doesn’t help, because the card’s BIN still says where it was issued, and entering an address you don’t live at breaks the issuer’s AVS check as well as Steam’s terms.

    Store country and currency: how they really change

    Steam ties prices and Wallet currency to the store country. If you move abroad for a long period, Steam’s help pages say you can update your store country when you make your first purchase with a payment method from your new country. Steam limits how often this can happen [VERIFY: Steam Store Country FAQ, change frequency, reported as roughly once every three months], and Steam Support says it cannot change the store country for you.

    This is deliberate. Regional pricing on Steam is set per country, and the Steam Subscriber Agreement does not allow users to disguise their country of residence to reach other regional prices. [VERIFY: exact Steam Subscriber Agreement clause on location and IP proxying] Accounts that do so risk purchase restrictions or worse. A VPN doesn’t change your store country anyway, and a card from another country doesn’t make you a resident there. The only legitimate way to change region is to actually move and pay with a local method.

    Your Steam Wallet is held in your store country’s currency. Funds you add are converted into that currency at the time of purchase and stay there. If your card is held in one currency and Steam charges in another, the network converts the amount and your provider may add a cross-currency fee. Check your card’s fee page before you buy so the total isn’t a surprise.

    Card-level declines once the region is right

    If your store country, location and card country all match and the purchase still fails, it is an ordinary card decline. The usual causes, in the order I check them:

    • Balance too low for the full amount. Steam charges the total including tax. On a prepaid card, any pending authorization from a previous failed attempt also reduces the available balance until it drops off.
    • AVS mismatch. The billing name, street and postcode must match what the issuer has for the card. Use the same address every time.
    • 3D Secure. In regions with strong customer authentication, Steam may show a 3DS challenge. If you miss the code window, the payment fails.
    • Prepaid or card-type rules. Some issuers block gaming merchants, and some programs decline certain merchant categories. The decline code is usually generic, such as 05 (“do not honor”).
    • Too many attempts. Repeated failed attempts can trigger a temporary purchase limit on the account. Wait, fix the cause, then try once. [VERIFY: Steam’s failed-purchase limit and timing]

    A step-by-step routine for adding a virtual card to Steam

    1.  Confirm your store country in your Steam account details. It should be your country of residence.

    2.  Check the card’s BIN country and type with a BIN lookup. If the country is not your store country, stop here and skip to step 7.

    3.  Enter the billing name and address exactly as the card issuer has them, in your country.

    4.  Fund the card above the purchase total to cover tax and any currency conversion.

    5.  Have your 3D Secure method ready before you click Purchase.

    6.  Buy once. If it fails, read the message, fix one thing and wait before trying again.

    7.  If the card doesn’t fit your country, use a local option: a card issued in your country, a local payment method Steam offers at checkout, or Steam Wallet codes sold by retailers for your region.

    Step 7 is the honest answer for many people in countries where local cards don’t work online. Steam Wallet codes bought from local retailers are designed for this, and they keep you inside Steam’s rules.

    Where a crypto-funded card fits, and where it doesn’t

    A crypto-funded prepaid card can work on Steam when its issuing country matches your store country. If it doesn’t, no setting will make it work legitimately, and you should use one of the local options above.

    VCCBuy’s Steam page describes one setup: a prepaid Visa or Mastercard funded with USDT or other supported coins, a billing name and address saved per card, and 3D Secure codes requested in the dashboard and shown for 10 minutes. The site also has a free BIN checker, so you can see the country, network and card type that Steam will see before you spend anything. Deposits are checked before they are credited, so top up before a sale starts rather than at checkout. Like any prepaid card, VCCBuy’s cards will be declined in some settings, and Steam makes its own checks on top of the issuer’s.

    FAQ

    Can I use a VPN or a foreign card to get a cheaper Steam region? No. Steam sets prices by country, requires a payment method from your country, and doesn’t allow users to disguise their location. Doing so can restrict your account. Change your store country only when you actually move, using a local payment method.

    Why does Steam say my billing address doesn’t match my country when the address is correct? Usually because the card itself was issued in another country, or your store country is not where you are buying from. Check the card’s BIN country. If it differs from your store country, use a local card, a local payment method or Steam Wallet codes for your region.

    Will Steam convert my card’s currency? Steam charges in your store country’s currency. If your card holds a different currency, the network converts it and your provider may add a fee. Wallet funds stay in the store currency.

    Conclusion

    Steam purchases fail on a virtual card mostly because the region signals don’t agree, not because the card is bad. Keep your store country honest, match the card’s country and billing address to it, and use local Wallet codes when they don’t match. If you want a crypto-funded card for gaming purchases in your own country, VCCBuy is one option to compare with local cards and Wallet codes.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about how platforms like Steam combine country, currency and card checks at checkout.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • Why the Second Month Fails: Prepaid Cards and Recurring Billing Explained

    Why the Second Month Fails: Prepaid Cards and Recurring Billing Explained

    You paid for the subscription, the first charge went through, and everything worked. Thirty days later you get an email: “We couldn’t process your payment.” Same card, same merchant, same amount, and this time it failed.

    Quick answer

    1. The first payment and the renewal are different kinds of transactions. You started the first one; the merchant starts the renewal on its own schedule, without you at the checkout.

    2. Most second-month failures come from timing: the renewal runs before the balance is topped up, or the amount is higher than you expected because of tax, currency or a price change.

    3. The rest come from card state (frozen, expired, over a limit) or the merchant’s own retry and verification rules.

    Two different transactions that look the same on your statement

    When you subscribe, you take part in a customer-initiated transaction (CIT). You type the card number, expiry and CVV, the merchant may run 3D Secure, and the issuer approves a charge while you are present.

    At that moment the merchant also asks to store your card for future use. Visa and Mastercard both run a stored-credential framework for this. The first transaction is flagged as the start of a recurring agreement, and the network returns a reference to that original transaction.

    Every renewal after that is a merchant-initiated transaction (MIT). You are not there. There is no CVV (merchants are not allowed to store it), and usually there is no 3D Secure challenge, because nobody is present to complete one. The merchant sends the stored card number, the expiry, the recurring flag and the reference to the original approval.

    That design changes what the issuer looks at:

    • With no fresh CVV or 3DS result, it relies on the card’s state, the available balance and its rules for recurring charges.
    • The charge happens at a time the merchant picks, often in a batch run in the merchant’s time zone.
    • If the card changed since month one, nothing warns you, because there is no checkout.

    So “it worked last month” proves the card and merchant were compatible on that day. It says nothing about the balance or card state on the renewal date.

    Where month two breaks

    Here is how the common failures map to what you see and what you can do about them. The response codes are standard ISO 8583 codes; individual merchants may show their own wording instead.

    Failure pointWhat usually happensTypical signalFix
    Balance short on renewal dayPrepaid balance is below the renewal amount when the merchant’s batch runsCode 51 (insufficient funds)Top up a few days before the renewal date, not on it
    Amount higher than month oneIntro price ended, tax was added, or the card is charged in a different currencyCode 51, even though “the price” is coveredCheck the plan’s full renewal price and currency
    Card frozenYou froze the card after signup and forgotGeneric decline, often 05 (do not honor) or a “restricted card” messageUnfreeze before the renewal, or move the subscription
    Card expired or replacedThe stored expiry no longer matchesCode 54 (expired card)Update the card in the merchant’s billing settings
    Card limit reachedA monthly spend or activity limit on the card is used upCode 61 or 65 (exceeds limit or frequency)Check the card’s limit against all charges due that month
    Merchant re-checks the cardSome merchants run a new verification or 3DS step at renewal, especially after a failed attemptRequest to “re-authenticate” or “update payment method”Log in and complete it while the card has funds
    Merchant’s risk rulesA renewal from a prepaid card is retried, flagged or blocked by the merchant’s processorPayment fails before reaching the issuerContact the merchant; use the method they accept

    Two of these deserve more detail, because they cause most of the confusion.

    Timing: the renewal doesn’t wait for your top-up

    A prepaid card has no credit line. If the balance is $14.50 and the renewal is $15.00, the issuer declines it, even if you plan to add funds an hour later. A credit card would have approved the charge and billed you at the end of the cycle.

    The renewal date isn’t always the one you expect. Some merchants bill on the signup anniversary in UTC, some move everyone to the first of the month after a plan change, and some charge a day early to leave room for retries.

    The amount: month one isn’t the real price

    Introductory pricing is the most common surprise. A plan that cost $1 or $5 for the first month renews at full price. A trial that cost nothing renews at the full monthly or annual amount, which on an annual plan can be twelve times what you budgeted.

    Sales tax or VAT may be added on top of the list price, depending on your billing address. And if the merchant charges in a currency other than your card’s, the converted amount moves a little every cycle.

    What retries do and don’t fix

    After a decline, most subscription merchants don’t give up. They run a dunning schedule: retry the charge after a few days, then again, then email you, and finally cancel or pause the account. The exact schedule is the merchant’s choice, and it varies widely.

    Retries help with soft declines. If the balance was short on Monday and you top up on Tuesday, Wednesday’s retry will probably go through. They don’t help with hard declines such as an expired card or a merchant block, where the same request will fail every time.

    Card networks also limit how often a merchant may retry a declined recurring charge, which is why some merchants stop sooner than you expect. The limits differ by network and region. [VERIFY: current Visa and Mastercard retry limits for declined MITs, if the editor wants a number]

    One thing worth knowing: a failed renewal doesn’t cancel the agreement. If the merchant’s retry succeeds a week later, you are charged then. If you meant to leave, cancel in the merchant’s account settings. A declined card is not a cancellation.

    A renewal-proof setup for prepaid cards

    The fix is mostly process. Use this checklist when you put a subscription on a prepaid card:

    1.  Write down the real renewal amount and currency. Find the price after any intro offer and include tax. On an annual plan, write down the annual figure.

    2.  Write down the renewal date and shift it two days earlier. Treat that earlier date as the deadline for having funds on the card.

    3.  Keep a buffer. Hold at least one full renewal amount above what you expect, so that a currency move or a small price rise doesn’t cause a decline.

    4.  One card per subscription, or one card per small group. If one card pays for ten services, one large charge can drain the balance before a small renewal arrives. A dedicated card makes the balance easy to reason about.

    5.  Check the card’s state before the date. Is it frozen? Is its monthly limit already used by other charges? Has it expired?

    6.  Keep the billing name and address the same as at signup. Merchants and processors compare what they stored with what they see at renewal and during any re-verification.

    7.  When a renewal fails, fix the cause, then let the merchant’s retry run, or trigger a retry from the billing page. Don’t add the same card again and again; repeated attempts can trip the merchant’s fraud rules.

    Where a crypto-funded prepaid card fits

    People paid in stablecoins often use prepaid cards for subscriptions because their local bank card fails on foreign merchants, or because they want each service on its own capped balance. The trade-off is no credit line, so the renewal date is a hard deadline.

    As one worked example, VCCBuy’s cards for subscriptions are prepaid Visa and Mastercard cards topped up with USDT, USDC and several other coins. Balances are held in USD, and deposits are checked before they are credited, so plan the top-up a few days ahead rather than on the renewal date. Each card can hold its own billing name and address, can be frozen and unfrozen, and lists its transactions, which makes a missed renewal easy to trace. It has no monthly fee, but there is a card issue fee and a top-up fee of 2–3% depending on the card.

    The limits apply here too. VCCBuy is not a bank and its cards are prepaid, so a merchant that refuses prepaid cards will refuse them on renewal as well. And freezing a card stops new charges; it doesn’t end your contract with the merchant. Bank-issued virtual cards, PayPal and gift-card balances are the usual alternatives, each with its own renewal behavior.

    FAQ

    Why did my subscription renew fine for months and then suddenly fail? Usually something changed on one side: a price increase, a currency change, a card that expired or was frozen, or a balance that ran lower than usual that month. Less often, the merchant changed processors or tightened its rules for prepaid cards.

    Does a failed renewal cancel my subscription? No. Most merchants retry for a period and then pause or cancel the account under their own terms. If you want to stop paying, cancel in the merchant’s account settings and keep the confirmation.

    Can I stop a merchant from charging me again by freezing the card? Freezing stops new authorizations while it is on, so the renewal will be declined. It doesn’t end the agreement, and the merchant may still consider the amount owed. Cancel properly first; use the freeze as a backstop.

    Conclusion

    The second month fails because the renewal is a different transaction from the signup: the merchant charges a stored card on its own schedule, with no CVV and no one at the checkout. On a prepaid card that turns the renewal date into a hard deadline. Write down the real amount and date, fund the card two days early, and give each subscription its own card. If you want a card per subscription funded from stablecoins, VCCBuy is one option to compare with your bank’s virtual cards.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about how recurring billing works behind the “payment failed” email, and how to set up renewals that don’t break.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • Office Moving Skokie Helps Businesses Relocate With Ease

    Office Moving Skokie Helps Businesses Relocate With Ease

     Asher Movers Local & Long Distance has expanded its moving services to support businesses planning office relocations in Skokie and surrounding communities. The new office moving service is designed to help businesses coordinate the transportation of office furniture, equipment, supplies and other workplace belongings during a commercial move.

    Office relocations can involve multiple logistical considerations, including coordinating moving schedules, handling workplace equipment and minimizing disruption to normal business operations. Asher Movers is offering commercial moving support to businesses seeking a structured approach to relocating their offices within Skokie or to another location.

    Addressing the Challenges of Office Relocation

    Moving an office can require more planning than a typical residential relocation. Businesses may need to move desks, chairs, filing systems, electronics, equipment and other workplace materials while coordinating the transition around employees and business operations.

    Asher Movers’ office moving services are intended to provide businesses with assistance throughout the physical relocation process. The company works with businesses to organize moving requirements based on the size, location and circumstances of each project.

    Company Response

    The addition of office moving services in Skokie expands Asher Movers’ existing commercial relocation capabilities. The company provides moving solutions for businesses as well as residential customers throughout Chicago and nearby suburbs.

    Additional details are available at: https://share.google/ARk5r1Acgk9hptlQg

    The service is available for businesses preparing for office changes ranging from smaller workplace moves to larger commercial relocations requiring additional planning and coordination.

    Office Moving Services in Skokie

    Asher Movers’ commercial moving capabilities can include:

    • Office furniture transportation
    • Commercial relocation assistance
    • Packing and preparation services
    • Loading and unloading
    • Transportation of workplace belongings
    • Moving assistance for businesses changing locations
    • Specialty moving solutions for items requiring additional care

    Businesses can discuss their specific relocation requirements with the company to determine an appropriate moving plan.

    Company Background

    Asher Movers is a Chicago-area moving company providing local and long-distance moving services for residential and commercial customers. Its services include local moving, long-distance moving, commercial relocation, apartment moving, packing, piano moving and specialty moving solutions.

    The company serves homeowners, businesses, students and military families throughout Chicago and nearby suburbs. Asher Movers states that its movers are licensed and insured and focuses on careful handling and customized moving solutions for different relocation needs.

    Executive Quote

    “Office relocations require coordination, careful handling and attention to the needs of the business,” said a representative of Asher Movers. “Our office moving service in Skokie is intended to give local businesses additional support as they transition from one workplace to another.”

    Future Outlook

    Asher Movers plans to continue providing moving and relocation services to customers throughout the Chicago area. The company’s expanded focus on office moving in Skokie reflects continued demand for commercial relocation assistance as local businesses adjust their workplace needs and locations.

    Businesses seeking information about office moving services in Skokie can contact Asher Movers directly to discuss their relocation requirements.

    About Asher Movers Local & Long Distance

    Asher Movers Local & Long Distance is a Chicago-area moving company providing local, long-distance and commercial relocation services. The company’s services include office and commercial moving, apartment moving, packing, piano moving and specialty moving solutions. Asher Movers serves customers throughout Chicago and nearby suburbs with customized moving services for residential and business relocations.

    Media Contact

    Asher Movers Local & Long Distance
    Email: info@ashermovers.com
    Phone: 773-638-4167
    Website: ashermovers.com